Monaco vs France for Wealthy Americans: Tax, Lifestyle, and the Cross-Border Traps

By Aurelio Maurici Co-Founder, Master of Business Law, Aix-Marseille Université III

Reviewed by Inès Guermouche, Avocate, Paris Bar Partner, Beaupère & Guermouche Avocats

Reviewed by Violette Beaupère, Avocate, Paris Bar Partner, Beaupère & Guermouche Avocats
Published Updated Last reviewed How we review

In this article
- Monaco vs France at a glance for American residents
- Why Monaco’s zero income tax does less for Americans than they expect
- The exclusion covers a salary, not a portfolio
- No US treaty means more withholding, not less
- What France actually taxes and where the treaty helps
- The residency you actually have to live: Monaco’s real bar
- The cross-border trap that catches people who straddle the border
- Who should lean toward Monaco and who is better off in France
- Where Americans get stuck choosing between Monaco and France
- Before you commit to either side of the border: a readiness check
- When you can handle this alone and when a consulting call pays off
- FAQ
- Conclusion
If you have the means to live anywhere on the Riviera, the Monaco vs France question comes up fast, and the honest answer surprises most Americans. Monaco levies no personal income tax on its residents, but for a US citizen that headline saves far less than it looks, because the United States taxes its citizens on their worldwide income no matter where they live. France, by contrast, has high headline taxes and a full income tax treaty with the United States that usually coordinates the two systems, so many Americans in France end up owing little or no extra US tax on income France has already taxed. Which side of the border wins depends on your income mix, how genuinely mobile you are, and whether you can accept Monaco’s cost of entry and its real presence rules. This article is for informational purposes only and does not constitute tax or legal advice. Tax rules are complex and change frequently: consult a qualified cross-border tax professional before making any filing or planning decisions. This article is for informational purposes only and does not constitute immigration or legal advice. Rules change, and your situation may differ: always verify current requirements with the relevant French authorities or a licensed immigration professional.
Monaco vs France at a glance for American residents
Here is how the two jurisdictions compare on the points that actually move the decision for a US citizen:
| Factor | Monaco | France |
|---|---|---|
| Personal income tax | None for non-French residents | Progressive, up to roughly 45 percent, plus surcharges and social levies |
| Capital gains tax | None on securities and most assets | Taxed, a flat tax of 12.8 percent plus 18.6 percent social levies (31.4 percent) applies to most investment income, while gains on real estate are taxed at 19 percent plus 17.2 percent social levies after holding-period allowances, with a surtax of 2 to 6 percent on taxable gains above 50,000 euros |
| Wealth and property tax | No wealth tax, no annual housing or property tax | Real estate wealth tax (IFI) on net French property above 1,300,000 euros |
| Inheritance, spouse and children | 0 percent in the direct line, on Monaco assets | Taxed, with forced heirship rules protecting children |
| Tax treaty with the United States | None | Yes, a full income tax treaty |
| French nationality (dual US and French citizens) | A French citizen who moved to Monaco is generally taxed by France as if still living there, and on worldwide real estate for the IFI | Taxed as any French resident |
| High-income minimum tax | None | Contribution of 3 to 4 percent above 250,000 euros of reference income (500,000 for a couple), plus a differential contribution that tops income tax up to 20 percent of income |
| Residency route (non-EU) | French long stay visa, then a Monaco residence card | French long stay visa, then a French residence permit |
| Minimum real presence | Genuine residence, 183 days per year for the tax certificate | Genuine residence, varies by permit |
| Cost of entry | Property in the world’s most expensive market plus a large bank deposit | High rents or purchase, but far below Monaco |
| What US citizenship adds | Full US tax on worldwide income, with little foreign tax to offset it | Full US filing, usually offset by French tax under the treaty |
The last row is the one Americans tend to skip, and it quietly rewrites the whole comparison. A British, German, or Middle Eastern national who moves to Monaco can genuinely stop paying income tax. A US citizen cannot, because American tax obligations follow the passport, not the address. That single fact is why the intuitive answer (Monaco is the obvious choice for a wealthy person) is often wrong for Americans, and why this comparison has to be run through the US lens before the French one.
If you are also a French citizen, the comparison can flip. Under the 1963 France-Monaco tax convention (article 7-1), French nationals who moved their home to Monaco are generally taxed by France as if they still lived there, and under article 7-3 French nationals who settled in Monaco from 1 January 1989 are liable to the IFI on all their real estate, in France, in Monaco and elsewhere (BOI-INT-CVB-MCO-10, paragraph 380). The relief for French citizens who hold another nationality applies only to those who moved to Monaco before 29 December 1995 and met further conditions, so it does not help someone who moves today.
Why Monaco’s zero income tax does less for Americans than they expect
Monaco’s income tax advantage is real, but for a US citizen it collides with citizenship-based taxation. The United States is one of the only countries that taxes its citizens on their worldwide income regardless of where they live, and the IRS confirms that Americans abroad have the same filing obligations as Americans at home. Moving to Monaco does not switch that off. You still file a US return every year, and you still owe US tax on income that Monaco chooses not to touch.
The exclusion covers a salary, not a portfolio
The tool most Americans reach for is the Foreign Earned Income Exclusion. For 2026 it lets a qualifying person exclude up to 132,900 dollars of foreign earned income from US tax. The catch that undoes the Monaco plan is in the word earned: the exclusion applies to salary, wages, and self-employment income, and it does nothing for dividends, interest, capital gains, or most rental income. Wealthy Americans rarely live on a salary. They live on a portfolio. That income is fully exposed to US tax whether you sit in Monaco or Manhattan.
In France, the same investment income is taxed by France, and those French taxes generate a foreign tax credit (and treaty relief) that usually wipes out the corresponding US bill. In Monaco there is almost no local income tax, which means almost no foreign tax to credit, which means the US tax stands with nothing to offset it. What we see most often is an American who moves to Monaco expecting a zero tax life and discovers, at the first US filing, that the US bill on their investment income is roughly what it would have been anywhere, only now they are paying Monaco prices to earn it.
No US treaty means more withholding, not less
Monaco has one of the narrowest tax treaty networks in Europe and no tax treaty with the United States. For an American with a large US equity portfolio, that has a concrete cost: US-source dividends paid to a Monaco resident who is not a US person are generally exposed to the standard 30 percent US withholding, rather than the reduced rate (commonly 15 percent) that residents of treaty countries such as France can claim. That withholding applies only to payments to foreign persons, so it does not apply to you as a US citizen, but it can matter for a non-US spouse or a foreign entity that holds the shares. If your wealth sits in US stocks and funds held through a non-US person or entity, Monaco can quietly cost you more on that income than France would, which is the opposite of what the brochures imply. This is also why the mechanics of investing as an American in France are worth understanding before you assume any European base solves your tax picture.
Moving to France doesn't end your US filing. It doubles it.
What Americans get wrong about moving to France, and the number, form or deadline that fixes it. Straight to your inbox.
One email a week. Real numbers, nothing else.
What France actually taxes and where the treaty helps
France taxes its residents on worldwide income at progressive rates that reach roughly 45 percent at the top, with a flat tax on most investment income of 12.8 percent plus 18.6 percent social levies (31.4 percent in 2026, with special rules for some placements), so on paper France looks brutal next to Monaco. The reason France still competes for wealthy Americans is the treaty. Because France taxes the income and the United States and France have a full income tax treaty, the US foreign tax credit and treaty provisions generally prevent the same income from being taxed twice, and for many Americans the French tax is high enough to cover the US tax on that income entirely. You pay a lot to France, but you often pay little or nothing extra to the IRS, and your total is not always far above what a US citizen effectively pays while living in Monaco once the US side is counted. The treaty does not clear everything automatically, though: for a US citizen resident in France, article 24 of the 1994 treaty gives a French tax credit equal to the French tax on certain US-source dividends, interest and royalties only under conditions (for example, when they are paid by the US government, by a listed company, or by a company in which you hold less than 10 percent of the votes), so the nature, source and payer of each income must be checked. The tax administration’s guidance on this credit, written for income received through a US partnership, adds that it is granted only if you can show that the US tax was paid, and that the French tax counted includes income tax, CSG, CRDS and the other social levies.
Where France does add a distinct cost is real estate. France applies a real estate wealth tax, the IFI, to households whose net taxable property is above 1,300,000 euros on 1 January, at progressive rates from 0.5 percent to 1.5 percent. A French tax resident is liable on their worldwide real estate; a non-resident is liable only on real estate located in France. A newcomer gets a break: someone who was not French tax resident in any of the five calendar years before arriving is taxed only on French property until 31 December of the fifth year after the year they became resident, and only after that on real estate worldwide (CGI art. 964). That distinction matters enormously for the Riviera dream, because it means a Monaco resident who buys a villa in France is still on the hook for French IFI on that villa if it crosses the threshold. In our experience this is the tax that catches people who thought crossing the border solved everything: they establish in Monaco, then buy the French property they actually wanted, and the French wealth tax follows the bricks.
Succession is the other place the two systems diverge sharply. Monaco charges no inheritance tax between spouses or in the direct line on Monaco-situated assets, while France applies inheritance tax and, importantly, forced heirship rules that reserve a portion of the estate for children. Which country’s civil law governs your estate is a separate question: under EU Regulation 650/2012 it is in principle the law of the country where you were habitually resident at death (article 21), unless you chose the law of your nationality (article 22), and when a foreign law applies that has no protective reserve for children, article 913 of the French Civil Code lets each child take a compensatory share from the assets located in France. On the tax side, article 750 ter of the French tax code also taxes assets an heir receives from abroad when the heir has been French tax resident for at least six of the ten years before the year of the inheritance. Separately, the 1978 France-US estate and gift tax treaty has its own domicile tie-breaker (article 4): a US citizen who is not also French, and who has been domiciled in France for less than five years in total over the seven years before death, is deemed domiciled only in the United States if they clearly intended to keep their US domicile, so the result depends on cumulative conditions and is never automatic. If estate planning is central to your decision, read how French inheritance rules work for Americans before assuming a French base is neutral for your heirs.
France also levies an annual tax on high-value real estate, and the rules shift sharply with how long you have been resident, which we break down in our guide to the IFI and the five-year exemption for new arrivals.
If the French villa is held through a company, including a Monaco company or a US LLC, a separate annual tax of 3 percent of the market value of the French buildings can apply to the entity (CGI art. 990 D). Exemptions exist (art. 990 E), among them for entities based in France, the EU or a country with an administrative assistance convention with France that file a yearly return by 15 May, but they depend on the entity’s seat and situation, so filing the return is not a universal exemption. Our guides on holding French property through an SCI and on French property taxes for US owners cover the rules for those structures.
Very high incomes face two more French charges. The exceptional contribution on high incomes adds 3 percent on the part of reference income between 250,000 and 500,000 euros for a single person (500,000 and 1,000,000 for a couple) and 4 percent above (CGI art. 223 sexies). The differential contribution (art. 224) applies from the same thresholds and tops up the income tax and that contribution to 20 percent of the income; for this test the benefit of tax credits provided by tax treaties is added back to the income tax, up to the tax due. In the year of arrival or departure the contribution is computed only on the income of the period of French residence.
A newcomer sent to work for a company in France may also benefit from the impatriate regime (CGI art. 155 B): for employees who were not French tax resident in the five previous calendar years, pay directly linked to the assignment is exempt (or 30 percent of pay, by option), and 50 percent of certain foreign passive income is exempt, until 31 December of the eighth year after taking up the post.
If you are leaning toward France, it is worth checking whether the 2026 wealth-tax debate should change your decision before you commit.
The residency you actually have to live: Monaco’s real bar
Monaco has no golden visa and no investment-for-residency scheme. It grants residence to people who can support themselves without local employment, hold suitable accommodation, and pass a security check, and for Americans the process runs through France first. Here is the real sequence:
-
Apply for a French long stay visa (a Type D “visa d’établissement” for Monaco) at the French consulate for your area, through the official France-Visas route for Monaco. Unless you have been established in France for more than a year, in which case you ask the French Embassy in Monaco for a transfer of residence, you must apply for this visa; it is what makes the Monaco application possible.
-
Secure accommodation in Monaco, by buying (you hold the title deed) or renting (a lease of at least 12 months), sized appropriately for your household.
-
Open a Monaco bank account and obtain the bank’s attestation of sufficient funds. There is no minimum amount fixed in law, but Monaco banks in practice require a substantial deposit before issuing the letter, an amount commonly cited around 500,000 euros and set by each institution.
-
File the residence card application with the Residents Section, attend the interview, and receive a temporary card (carte de séjour temporaire) valid for one year.
-
Renew the temporary card annually, move to an ordinary card after three years, and become eligible for the ten year privileged card after ten years of genuine, effective residence.
The word doing the heavy lifting is genuine. A Monaco residence card is an immigration permit; it is not the same as a Monaco tax residency certificate, and it is the certificate that lets you assert Monaco tax residency against another country. For that certificate you must meet one or more of these conditions: spending more than 183 days per year in the Principality, having the main centre of your activities there, or spending your longest stay of the year there, evidenced by real utility consumption, local bank activity, and daily life. The administrative card renewal expects meaningful presence too, typically at least a few months a year for the first card, with stricter expectations as you move up. Monaco is now thorough about checking that residents actually live there, and a card obtained for status but not backed by presence is the weakest position of all.
France is no different in one respect, because it too has no buy-in scheme, and our guide to the real French residency routes for wealthy Americans explains what you apply for instead.
The cross-border trap that catches people who straddle the border
This is the mistake the Riviera is built for, and it takes two forms. The first is about where your work happens. Monaco sits minutes from the French communes of Cap d’Ail, Beausoleil, and Roquebrune, and it is tempting to base yourself in Monaco on paper while your working life, or your staff, actually sits on the French side. French law does not follow the contract; it follows where the work is performed. A worker who is habitually employed on French soil falls under the French social security system, and a Monaco employer whose employee works in France must pay the mandatory French contributions to URSSAF, not to Monaco. The temporary posting procedure (détachement) that lets a worker stay on the Monaco system exists only for genuinely temporary missions with the right paperwork; someone hired to work in France does not qualify. Whether you qualify comes down to your specific contract and paperwork, and a consulting call will settle it before you plan around the wrong assumption.
In practice, this is where the household staff arrangement blows up. What we see most often is an American who sets up a Monaco employment contract for a nanny, a driver, or a housekeeper who in reality lives and works at the family’s French address, in the belief that a Monaco contract avoids France’s heavy employer charges. It does not. The correct affiliation is French, and papering a France-based job onto a Monaco contract is undeclared work, which carries French penalties and back-charges.
The second form of the trap is about you. If you claim Monaco residence but keep the true center of your life in France, French tax residency can pull you back in. Under French law a person is French tax resident if they meet any one of three alternative tests: their home or main place of stay is in France, they carry on their main professional activity in France, or the center of their economic interests is in France. Meeting a single test is enough, the 183 day figure is only a rough shortcut for the first one, and nationality is irrelevant. The law lists the home (foyer) and the main place of stay as two separate alternatives, so spending most nights in Monaco does not by itself rule out a French home counting as yours. A tax treaty takes you out of French residence only when it itself treats you as non-resident in France, and the France-US treaty’s tie-breaker (article 4) settles residence between France and the United States, not between France and Monaco. So an American who sleeps in Monaco a few nights but runs a business from a French home, keeps the family in a French house, or holds the bulk of income-producing assets in France, can be reclassified as a French tax resident, taxed by France on worldwide income, and exposed to French IFI on worldwide real estate. Straddling the border loosely is the most expensive way to get this wrong.
Leaving France for Monaco can also trigger the exit tax (CGI art. 167 bis). It concerns people who were French tax resident for at least six of the ten years before the move and who hold shares worth more than 800,000 euros, or shares representing at least 50 percent of a company’s profits. Payment is deferred automatically when the destination is an EU state or a state that has the required administrative and recovery assistance conventions with France, and on express request, with guarantees of 12.8 percent of the gains, in other cases, so leaving does not by itself mean paying at once. Reporting duties and guarantees still have to be planned before departure.
Sorting a genuine Monaco base from a French tax residency, and structuring staff, property, and income so the two sides of the border do not collide, is exactly the kind of decision where a short conversation early saves a costly reclassification later. Our one-to-one consulting call is built to pressure-test that decision before you sign a lease, move a business, or hire anyone, so you commit to a structure that survives scrutiny on both sides.
Who should lean toward Monaco and who is better off in France
There is no single right answer, but the profiles sort cleanly once the US layer is included:
| Your situation | Base that usually fits | Why |
|---|---|---|
| Very high income that is mostly non-US and genuinely mobile | Monaco | Little US tax exposure to begin with, so Monaco’s 0 percent is not neutralized |
| Wealth mostly in a US investment portfolio | France | US taxes the portfolio anyway; French tax generates credits |
| Retiree on a fixed US pension | France | The treaty coordinates well for retirees, and the cost of entry is a fraction of Monaco’s |
| Founder or remote worker still tied to the US | France | Income is largely US-taxed regardless; France is far cheaper to live in legitimately |
| Family with school-age children | France | Broader schooling options and cost, without Monaco’s presence and property bar |
Two edge cases are worth naming, because wealthy Americans raise them constantly. The first is consumption tax, which is a non-difference: Monaco sits inside the French VAT system and applies the same 20 percent standard rate as France, so what you pay in tax on cars, dining, and everyday spending is essentially identical on both sides of the border. The second is the drastic option some consider: renouncing US citizenship to escape citizenship-based taxation altogether. That is not a light move. It is irreversible, it can trigger a US exit tax for wealthier “covered expatriates” (with net-worth and tax-liability thresholds you should verify against current figures), and it does not open the Monaco door either, because Monaco does not permit dual citizenship and its naturalization, available only after ten years of residence, is rare and granted at the Prince’s discretion. For almost everyone, the realistic choice remains where to be taxed, not whether to keep the passport.
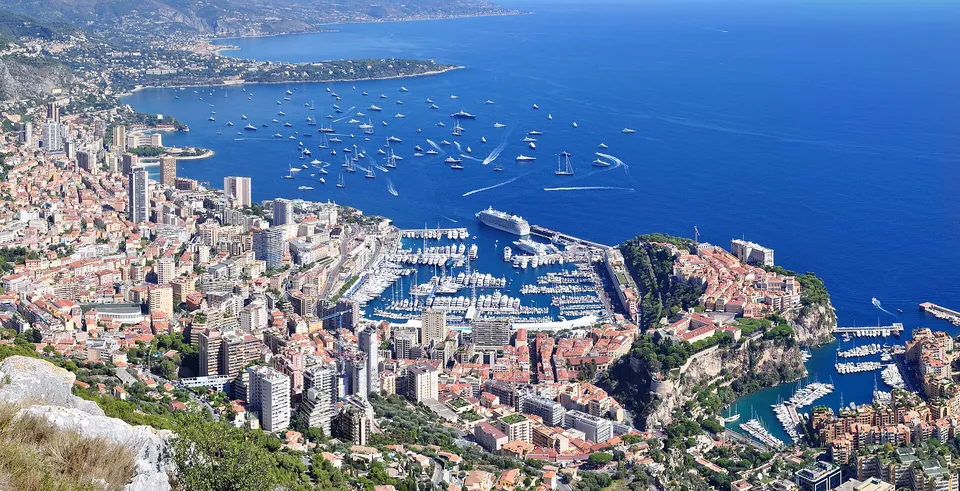
The pattern underneath the table is simple. Monaco’s advantage is largest when you have a lot of income the US does not already tax and you can truly live in a two square kilometer principality most of the year. The moment your income is US-taxed anyway (a US portfolio, US-source dividends, a US business), Monaco’s headline benefit shrinks toward zero while its costs stay very real, and France, high taxes and all, often nets out better once the treaty does its work. If your heart is set on the coast either way, it is worth mapping where to base yourself on the French Riviera, because the lifestyle you are paying Monaco for is available a few kilometers away at a very different price.
Where Americans get stuck choosing between Monaco and France
The friction is rarely about lifestyle, which both places deliver. It is about assumptions that only surface once money and paperwork move.
The first is treating Monaco’s zero income tax as a US tax solution. In our experience this is the single most common miscalculation: the decision gets made on the Monaco number alone, the US return is an afterthought, and the saving evaporates when the portfolio is taxed by the IRS regardless. The US side has to be modeled first, not last.
The second is underestimating the presence bar. What we see most often is someone who wants the Monaco address for its status but plans to spend half the year elsewhere, then discovers that the residence card renewal and, more sharply, the tax residency certificate both require genuine, documented presence, and that a French home or French business can trigger French tax residency under the economic-interests test no matter what the Monaco card says.
The third is the entry cost shock. Monaco is the most expensive property market in the world, and the bank deposit needed to obtain the residency attestation is a genuine gate, not a formality. Americans coming from even the priciest US markets routinely underestimate both. None of these are reasons to avoid Monaco; they are reasons to run the numbers with clear eyes before committing.
Before you commit to either side of the border: a readiness check
Work through this list before you choose a base or sign anything:
-
Model the US side first: run your worldwide income through a US return under both scenarios, so you know your real US tax before the Monaco 0 percent tempts you.
-
Map your income mix: separate earned income (which the exclusion can shelter) from investment income (which it cannot), and flag how much is US-source.
-
Price the true cost of entry for Monaco: property in the world’s dearest market plus the bank deposit the residency attestation requires.
-
Confirm you can meet genuine presence: be honest about how many days a year you will actually spend in Monaco, against the 183 day tax-certificate standard.
-
Check where your work is really performed: if you or your staff operate on French soil, plan for French social security and labor rules, not Monaco ones.
-
If you will keep French real estate, model French IFI on it above 1,300,000 euros, whichever side of the border you live on.
-
Break your US state tax residency before you leave, especially from an aggressive state, so a US state does not keep taxing you: see how to break US state tax residency.
-
Get your specific situation reviewed by a cross-border professional: the France and Monaco convention, US treaty position, and your asset mix interact in ways generic guides cannot resolve.
When you can handle this alone and when a consulting call pays off
You can reasonably run this yourself when the situation is simple: your income is straightforward, you are choosing one clear base and will genuinely live there, you have modeled the US side, and you are not trying to keep a foot on each side of the border. Plenty of Americans make a clean, well-informed choice without help.
A conversation earns its keep the moment the picture gets mixed: a US-heavy portfolio, a business you run remotely, household staff, a French property alongside a Monaco address, or any plan that straddles the frontier. Those are the cases where a small structuring decision made early prevents a large, retroactive tax problem. A one-to-one consulting call with EasyFranceNow is designed to pressure-test the Monaco versus France decision against your actual income, assets, and presence, and to help you build a structure that holds up to French and Monaco scrutiny rather than one that looks good only until someone checks. It is guidance on your real situation, not a substitute for your own accountant or attorney, and for a decision this consequential it is usually the cheapest step you take.
FAQ
Do Americans pay income tax if they live in Monaco?
Not to Monaco, but yes to the United States. Monaco levies no personal income tax on residents who are not French nationals, so an American resident owes Monaco nothing on income. However, the United States taxes its citizens on their worldwide income regardless of where they live, so a US citizen in Monaco still files a US return and still owes US tax on income Monaco does not tax. The Foreign Earned Income Exclusion can shelter up to 132,900 dollars of earned income for 2026, but it does not cover dividends, interest, or capital gains, which is exactly the income most wealthy Americans rely on. In short, Monaco removes the local tax, not the US one.
How many days do you have to spend in Monaco to keep residency and tax residency?
There are two different thresholds, and they are often confused. To keep the Monaco residence card, you must maintain genuine, effective residence, typically at least a few months a year for the first card, with stricter expectations at the higher card levels. To obtain the separate Monaco tax residency certificate, the one that lets you assert Monaco tax status to another country, the conditions are spending more than 183 days per year in the Principality, having the main centre of your activities there, or spending your longest stay of the year there (one or more is enough), backed by real evidence of daily life. Because the exact expectations are discretionary and evolving, confirm your situation directly with the Monaco authorities before relying on either figure.
Can I live in Monaco but keep a house on the French Riviera?
You can own the house, but you have to watch two French rules. First, French real estate above 1,300,000 euros in net value is subject to the French IFI wealth tax even for non-residents, so a Riviera villa can be taxed by France while you live in Monaco. Second, and more serious, if that French home becomes your real center of life, France can treat you as a French tax resident under its home or economic-interests tests and tax your worldwide income, regardless of your Monaco card. Keeping a French property is fine; letting it quietly become the true center of your life is what triggers French taxation. This is a situation to structure deliberately with professional advice.
Is it worth getting professional help to decide between Monaco and France?
For a simple, single-base move it may not be. For most wealthy Americans weighing Monaco against France it usually is, because the decision turns on how US citizenship-based taxation, the France and Monaco rules, and the US treaty interact with your specific assets, and getting that wrong is expensive to reverse. Our consulting call is built precisely for this: it models both bases against your real income and presence, flags the cross-border traps before you commit, and helps you choose a structure that survives scrutiny. It complements your own accountant and attorney rather than replacing them, and for a decision of this size the cost of an hour of clarity is small next to the cost of a reclassification.
Conclusion
The Monaco vs France decision looks like a tax question and is really a US tax question wearing a Riviera disguise. Monaco’s zero income tax is genuine, but American citizenship-based taxation, Monaco’s lack of a US treaty, and its high cost of entry mean the saving is muted for US citizens and can even reverse for those living off a US portfolio. France’s high taxes are coordinated by a treaty that often leaves Americans owing little extra to the IRS, at a fraction of Monaco’s entry cost. The right base depends on how much of your income the US already taxes and how genuinely you can live where you claim to, and the one outcome to avoid is straddling the border loosely enough to be taxed by both. If you want to make that call with your real numbers rather than the brochure version, a consulting call with EasyFranceNow will map Monaco against France for your situation and help you commit to a structure that holds.
What worries you most about the move?
Moving to France doesn't end your US filing. It doubles it.
What Americans get wrong about moving to France, and the number, form or deadline that fixes it. Straight to your inbox.
One email a week. Real numbers, nothing else.
Written by
Aurelio Maurici
Co-Founder, EasyFranceNow
Aurelio Maurici is a French entrepreneur and co-founder of EasyFranceNow. His work focuses on the intersection of French administration, banking constraints affecting U.S. nationals, tax residency and cross-border reporting, healthcare enrollment, and the procedural realities Americans encounter while settling in France.
Reviewed for factual accuracy
Inès Guermouche
Avocate, Paris Bar
Partner, Beaupère & Guermouche Avocats
Reviewed for factual accuracy
Violette Beaupère
Avocate, Paris Bar
Partner, Beaupère & Guermouche Avocats
Inès Guermouche and Violette Beaupère reviewed this guide for factual accuracy on Oct 30, 2026. They do not write our content and have no editorial control over our recommendations. A review confirms this guide is factually accurate in general; it is not financial, tax or legal advice for your situation.
Violette Beaupère reviews selected articles for factual accuracy, together with Inès Guermouche. Their review covers French domestic law and the tax treaties concluded by France only, and takes no position on US domestic law, including IRS classification and US reporting forms.
How we review


